Mortgage Refinance · Toronto & GTA
Mortgage refinance in Toronto & the GTA.
Access your home equity, consolidate high-interest debt, or restructure your mortgage with options from multiple lenders — reviewed by a licensed broker, not an algorithm.
What Is Refinancing?
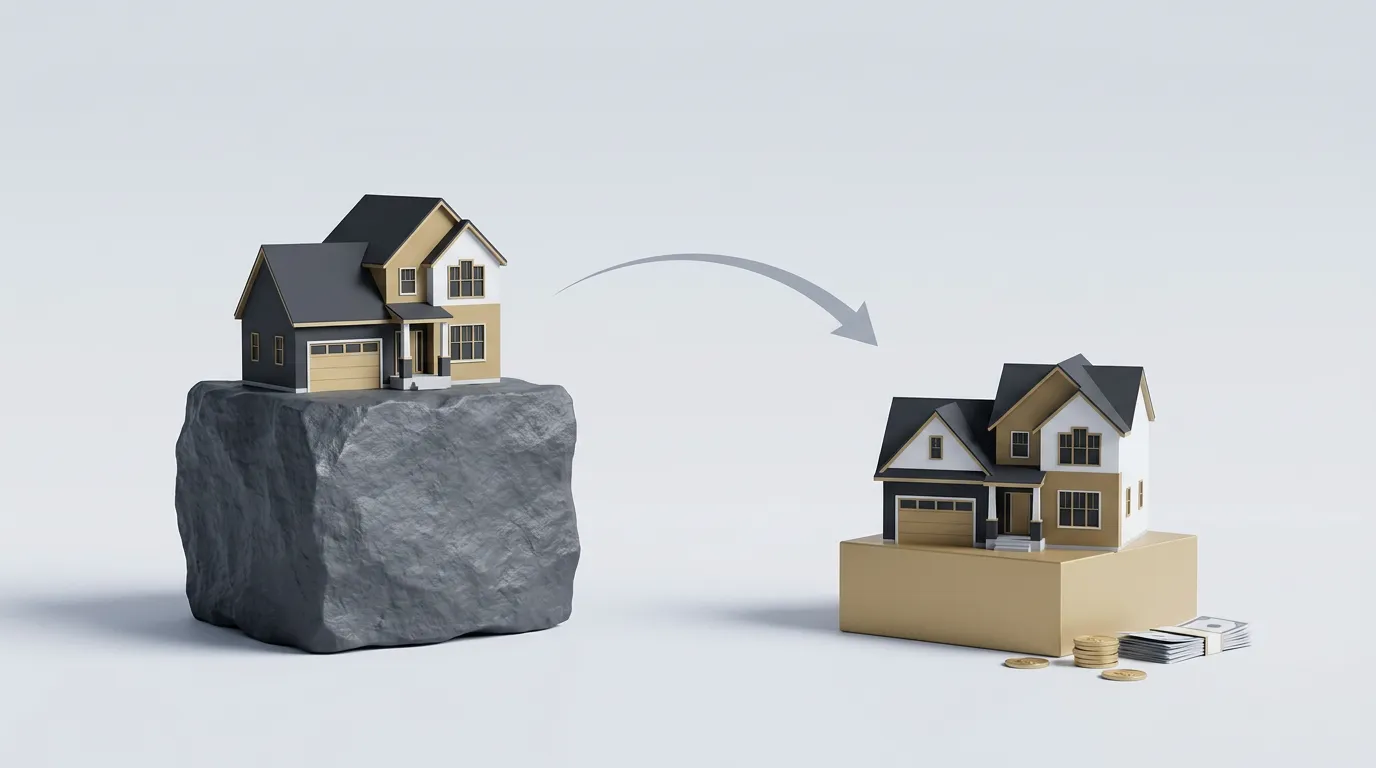
Same home. A better mortgage.
Refinancing means replacing your current mortgage with a new one — on new terms, at a new rate, or for a larger amount so you can unlock the equity you've built.
Replace
Your existing mortgage is paid out and replaced by a new one — often at a better rate or with better terms.
Restructure
Change your amortization, switch fixed to variable, or reset your term to fit where life is now.
Release
Borrow up to 80% of your home's value and take the difference as cash for debt, renovations, or investing.
Why Now
Rates are moving. Your mortgage shouldn't be standing still.
The market has shifted. Homeowners who locked in higher rates a few years ago are now leaving real money on the table every month.
Lower your monthly payment
A half-point rate drop can save hundreds a month. Over a 5-year term, that's real money back in your pocket.
Tap into your home equity
Your home has likely gained value. Access it for renovations, investments, tuition — whatever matters most.
Simplify your debt
Roll high-interest credit cards and lines of credit into one low mortgage payment.
Fixed 5-year
Call us
for today's verified rate
Variable
Call us
for today's verified rate
HELOC
Prime+
flexible options
We only publish rates once they have been verified against a current lender rate sheet. Call or book an appointment for today's rates for your situation. Mortgage Made Better Inc., FSRA Licence #13747.
Refinance Calculator
See exactly what refinancing saves you.
Move the sliders to match your mortgage. No personal information required — your savings update instantly.
Your current mortgage
Other debts
$15,000
Roll credit cards, lines of credit or loans into your mortgage at a lower rate.
Today vs. refinanced
Average rate
5.93%
on $495,000
Example rate
4.50%
For illustration, not an offer
Uses an example rate for illustration. Your actual rate depends on qualification and lender approval.
You could save every month
$623
Paying now
$3,569
mortgage + debts, avg. 5.93%
New payment
$2,946
per month at 4.50%
Now: $3,119 mortgage + $450 in debt payments. After: one payment on $495,000.
That's $7,475 a year, or $37,373 over a 5-year term.
Keep paying $3,569 instead.
Put your $623/mo saving back into the mortgage as an extra payment.
Total interest saved
$148,361
vs. keeping things as they are
Mortgage-free in
16 yr 4 mo
5 yr 8 mo sooner
Extra interest saved
$80,650
vs. the new minimum payment
Interest over the remaining 22 years
For illustration only. Uses Canadian mortgage convention (compounded semi-annually). Other debts are assumed to compound monthly at the payment you enter. New rate is our current advertised variable rate and can change. Excludes prepayment penalties, appraisal, and legal fees.
How It Works
Simple from start to finish.
We handle the complexity. You make the decisions.
Apply in minutes
Start online. No paperwork upfront, no commitment.
We do the shopping
Your broker compares banks, credit unions, and alternative lenders in one pass.
Get a clear answer fast
Your best options with honest numbers — including a break-even analysis if there's a penalty.
Close and move on
We handle the paperwork end to end. Most refinances close within 2–4 weeks.
Who It May Suit
Is a refinance right for you?
May suit you if
- Your mortgage is renewing soon or your prepayment penalty is small relative to the savings.
- You want the lowest available rate on the equity you borrow, at first-mortgage pricing.
- You want to roll high-interest debt into one payment and can qualify under the stress test.
- You want to change your amortization, switch between fixed and variable, or restructure your term.
May not be the best fit if
- Your current rate is well below today's rates and you would lose it by breaking the mortgage.
- Breaking your mortgage would trigger a large interest rate differential penalty.
- You only need a small amount, or the funds for a short period.
- You don't currently meet bank qualification for credit, income or debt ratios.
How Repayment Works
What paying it back looks like.
A refinance replaces your current mortgage with a new, larger one. You end up with a single mortgage and a single payment, usually spread over a longer amortization than a second mortgage or HELOC.
One blended payment
Your existing balance and the new funds are combined into one mortgage with regular principal and interest payments.
Up to 30-year amortization
Refinances are typically amortized over up to 30 years, which keeps payments lower but increases total interest.
New term and rate
You choose a new term, commonly 1 to 5 years, at a fixed or variable rate, and renew at the end of each term.
Prepayment privileges
Most lenders let you prepay 10% to 20% a year without penalty, so you can pay down the borrowed equity faster.
Costs & Risks
Know the full cost before you borrow.
We put every fee and trade-off in writing before you commit, so you can compare options on total cost rather than rate alone.
Costs to expect
Prepayment penalty
Breaking a mortgage early usually costs three months of interest or an interest rate differential, whichever is higher for fixed rates.
Appraisal
Lenders typically require an appraisal to confirm your home value. Some cover the cost.
Legal and discharge fees
A lawyer registers the new mortgage, and your current lender may charge a discharge fee.
Possible lender fees
Alternative lenders may charge a lender or brokerage fee where bank options are not available.
Risks to weigh
More total interest
Spreading consumer debt over a long amortization can lower the payment but increase the total interest you pay.
Losing a low rate
If your current rate is lower than today’s, the new rate applies to your whole balance, not just the new funds.
Debt can return
Consolidation works best when the cleared credit cards and lines are not run up again.
Your home is the security
Borrowing more against your home reduces your equity and increases what is owed if you sell.
When an Alternative May Be Preferable
Sometimes a different route costs less.
A refinance is one tool among several. These are the situations where we would usually look at another option first.
Complex Files Welcome
Your situation isn't unique. We've seen it.
We work with lenders who go beyond the standard checklist. Here's what we deal with every week.
High debt load
Consolidate everything into one manageable payment.
Self-employed income
Alternative-doc lenders who understand how you actually earn.
Credit challenges
Lenders for bruised credit — not just perfect scores.
CRA arrears
Can often be paid out directly in your refinance at closing.
Prepayment penalties
A break-even analysis shows whether breaking makes sense.
Appraisal concerns
Pre-review and market analysis before anything is submitted.
Still weighing it up?
Not sure if refinancing makes sense?
We'll help you compare the costs, benefits and alternatives — including any penalty — before you make a decision.
Ways to Access Your Equity
Three routes. One honest comparison.
Our Lender Network & Service Areas
We shop the market. You pick the winner.
Your bank has one rate. We compare across banks, credit unions, and alternative lenders — and we're not paid more for any particular one.
See your optionsToronto
Scarborough, North York, Etobicoke, Downtown
Durham
Pickering, Ajax, Whitby, Oshawa
York Region
Markham, Richmond Hill, Vaughan
Peel
Mississauga, Brampton, Caledon
Common Questions
Things people always ask.
It depends on your current rate, your balance, and what lenders are offering today. Even a 0.5% reduction on a $500K mortgage saves roughly $150/month. We'll show you exact numbers based on your situation — no guessing.
Not necessarily. We work with lenders across the credit spectrum — prime, near-prime, and alternative. Your credit score matters, but it's not the only factor. Equity in your home can open a lot of doors.
Totally workable. We have lenders who use stated income, bank statement programs, or alternative documentation. Being self-employed doesn't disqualify you — it just means a different set of lenders.
Yes, in many cases. CRA debt can be paid out at closing as part of the refinance. This is one of the more common scenarios we handle — and it's often a huge relief for homeowners who owe back taxes.
Breaking your mortgage early usually costs something. We run a break-even analysis upfront so you know exactly when you'd come out ahead — and whether it's worth it given your goals and timeline.
Most refinances close in 2–4 weeks from application. We can move faster when there's urgency. The biggest variable is usually getting the appraisal scheduled — we help coordinate that too.
Take the First Step
Let's build your refinance strategy.
Whether you're consolidating debt, accessing equity, renovating or restructuring your mortgage, we'll help you explore your options with clarity and no obligation.
Free service, no obligation. Licensed mortgage brokerage — FSRA #13747. Refinancing may involve prepayment penalties, legal, appraisal or lender fees.
Explore your refinance options
Takes about 60 seconds. A licensed broker follows up within one business day.